
Retirement Planning by the Decade: 50–55, 55–60 and 60–65
Retirement planning changes as the runway gets shorter. A practical framework for the questions worth asking from 50 through 65.
Retirement planning at 52 should not look exactly like retirement planning at 63.
The closer the date gets, the more the conversation shifts from accumulation to decisions.
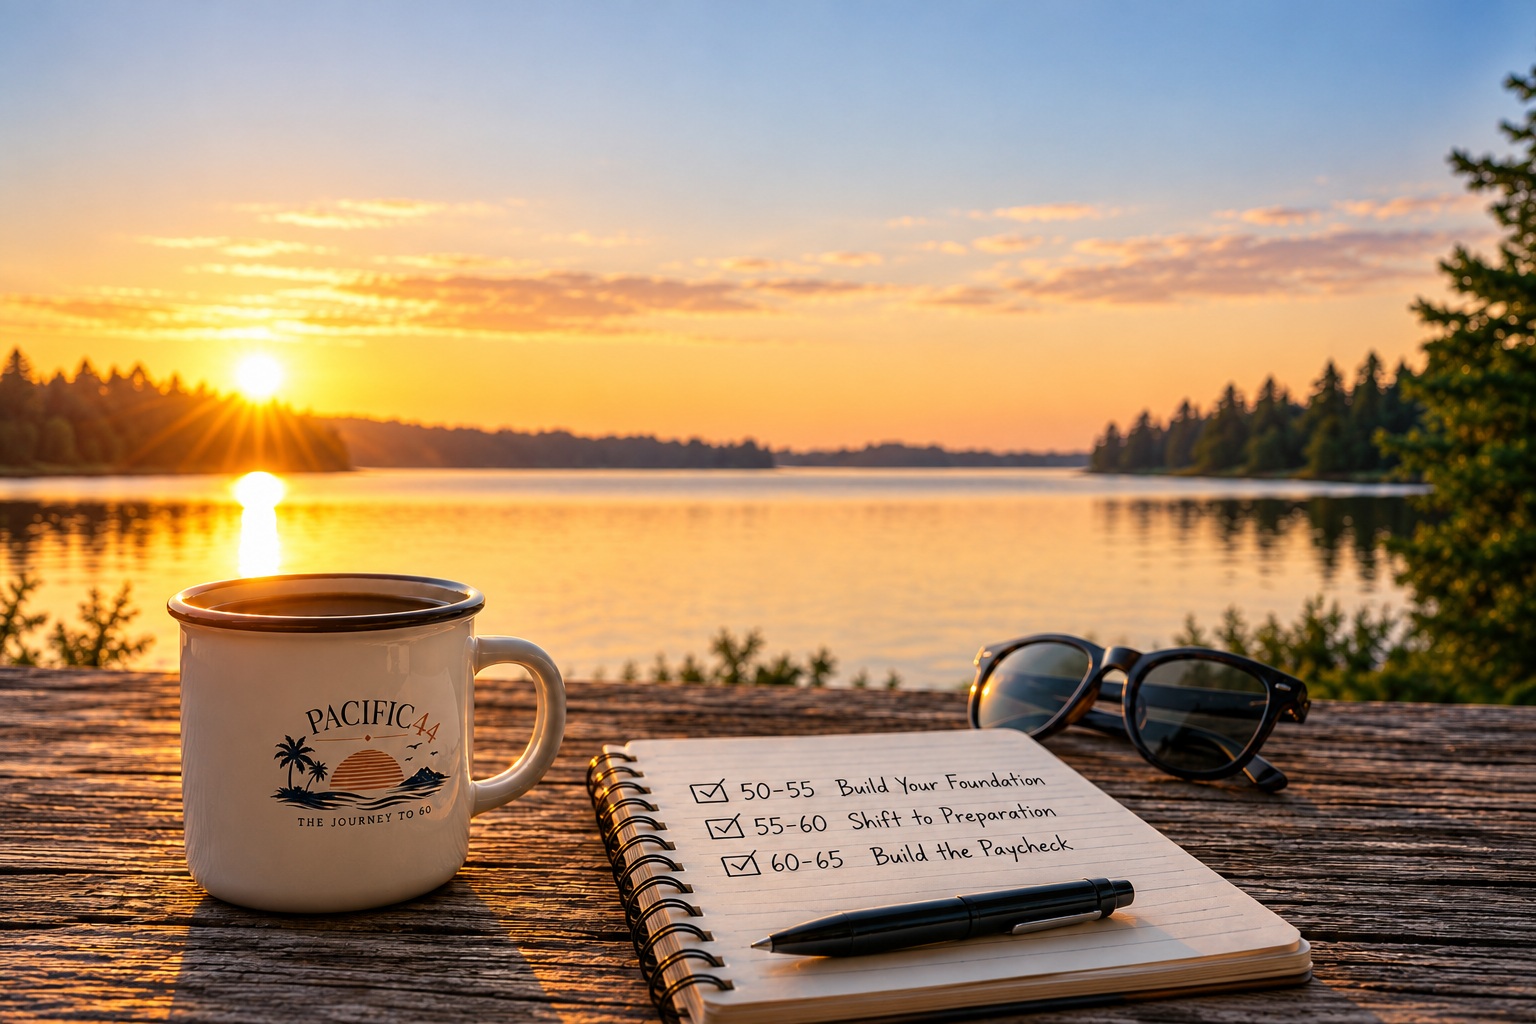
Ages 50–55: Build Options
This is a good window to understand what you actually have, what you owe and what kind of retirement you are trying to build.
Increase savings where possible. Review debt. Estimate Social Security. Think about housing. Start paying attention to healthcare instead of treating it as a problem for later.
Ages 55–60: Test the Plan
Now the questions become more concrete.
Could your spending work on the income you expect after work? Does your current home still make sense? Are there major expenses you want to handle before retirement? What happens if one spouse retires before the other?
This is also a good time to practice living on the budget you think you will use later.
Ages 60–65: Coordinate the Decisions
At this stage, Social Security timing, Medicare, employer coverage, taxes, retirement-account withdrawals and the exact retirement date begin interacting with one another.
The goal is not simply to reach a number. It is to make the pieces work together.
The closer retirement gets, the less useful vague planning becomes. Turn the dream into dates, dollars and choices.
— Allen S. Robinson
The Pacific44 Journal
Image
Gallery.

Join the Journey!
Stories, places, music, ideas & inspiration for the journey to 60 and beyond — delivered from Pacific44.
Explore
Related posts.
Follow the
Journey.
@pacific44_lifestyle